Thank you for attending!The workshop took place on Monday 12 October 2026. We hope to see you again.
Macroeconomic and Financial Modelling in an Era of Extremes
Date: Monday 12 October 2026
Venue: The Riverside Room, The Guildhall, York
About
This workshop brings together leading experts on macroeconomic and financial modelling to discuss recent advances in the modelling of extreme events. The workshop will be of interest to academic researchers at all levels, policymakers and practitioners.
Programme
09:30 – 10:00Morning coffee, followed by opening remarks by Michael Thornton
10:00 – 10:30Contagion and Immunisation: Directional Comoment Tests
Renee Fry-McKibbin
Australian National University
Renee Fry-McKibbin
Australian National University
10:30 – 11:00Search Effort, Screening Capacity, and the Matching Function: Evidence from Online Vacancies
Tho Pham
University of York
Tho Pham
University of York
11:00 – 11:30Equilibrium Treatment Effects with Network Interference and Latent Factors
Yongcheol Shin
University of York
Yongcheol Shin
University of York
11:30 – 11:50Coffee break
11:50 – 12:20Common and Hazard-Specific Variation in U.S. Natural Disaster Losses
Matthew Greenwood-Nimmo
University of Melbourne
Matthew Greenwood-Nimmo
University of Melbourne
12:20 – 12:50Semiparametric forecast comparison in unstable environments
Laura Coroneo
University of York
Laura Coroneo
University of York
12:50 – 14:00Lunch
14:00 – 14:30Quantile Inflation Spillover Networks of the G7: Transmission and Propagation
Ze-Yu Zhong
Melbourne Business School
Ze-Yu Zhong
Melbourne Business School
14:30 – 15:00Bootstrap Inference in Factor-Augmented Regressions with Weak Factors
Takashi Yamagata
University of York
Takashi Yamagata
University of York
15:00 – 15:30Advancing Multi-Dimensional Spatial/Network Econometrics: The MSAR Framework
Chaowen Zheng
University of Southampton
Chaowen Zheng
University of Southampton
15:30 – 15:50Coffee break
15:50 – 16:20Nonparametric Dyadic Quantile Regression
Francesco Bravo
University of York
Francesco Bravo
University of York
16:20 – 16:50The Quantile Vector Autoregressive Model with Observed Common Factors
Daniel Tiong
University of Melbourne
Daniel Tiong
University of Melbourne
16:50 – 17:20Rate-Adaptive Inference for Smoothed Instrumental Variable Quantile Regression
Byunghoon Kang
Lancaster University
Byunghoon Kang
Lancaster University
Dinner
Venue
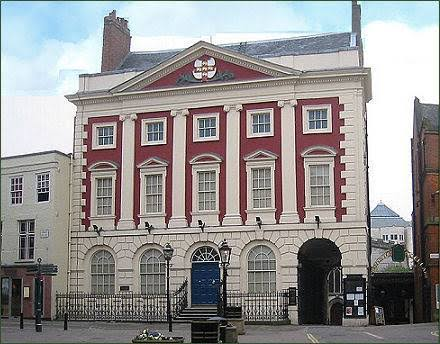
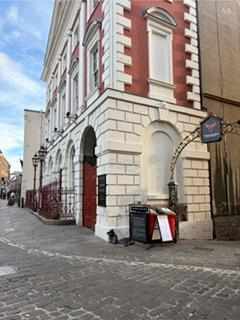
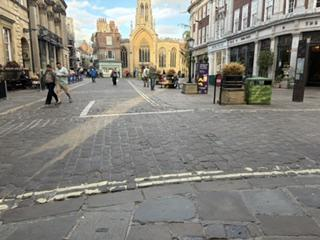
The Entrance to the Guildhall:
From the Mansion House building, walk through the archway to the bottom.
Practical Information
- Wi-Fi: please use the UoY-Fi network
Local Organiser
Yongcheol Shin (University of York)
Organising Committee
- Tomohiro Ando (Melbourne Business School)
- Renee Fry-McKibbin (Australian National University)
- Matthew Greenwood-Nimmo (University of Melbourne)
- Yongcheol Shin (University of York)
Contact
Yongcheol Shin (Workshop) yongcheol.shin@york.ac.uk